
AI Agents for R and D Tax Credit Substantiation
The credit is calculated from records that were never created for tax. Substantiation is a documentation exercise happening a year too late.
- Claims are rarely challenged on the calculation. They are challenged on whether the activity qualified and whether the records support it.
- Contemporaneous evidence carries far more weight than a narrative written after year end from memory.
- Cost linkage is the second gap: connecting qualifying activity to specific payroll, contractor and supply costs.
- The work is usually done in a compressed period with a specialist, which limits how much evidence can realistically be gathered.
- ChatFin collects the evidence as the work happens and assembles the file so the specialist starts from documentation rather than interviews.
Research incentives reward activity that has already happened, and they are examined on documentation that was rarely created with an examination in mind.
The typical process runs backwards: engage a specialist after year end, interview engineers about work from ten months ago, write project narratives, and allocate cost on estimates. It produces a claim, and it produces a fragile evidence base.
This page covers what substantiation actually requires, why contemporaneous records matter so much, and how a governed agent can collect the evidence while the work is being done.
What actually gets tested
Examination focuses on whether the activity meets the qualifying criteria and whether the costs claimed relate to that activity.
Both are evidence questions. A well reasoned narrative written after the fact is weaker than a set of records created while the work was underway, even when both describe the same project.
The records already exist
Engineering teams generate documentation continuously: issue descriptions, design discussions, test results, failed approaches and decision records.
Failed approaches are particularly valuable, because they are direct evidence of technical uncertainty and experimentation, and they are exactly what gets discarded when narratives are written afterwards.
Capturing that material as it is created costs almost nothing. Reconstructing it a year later costs a specialist engagement and produces a weaker file.
Records created for engineering, not for tax
Technical discussions, test results and abandoned approaches live in project systems and chat histories. Payroll and contractor cost lives in finance. Neither was captured with an examination in mind, and both decay quickly.
What the agent needs to see
Ledger detail from the ERP, plus project records and technical notes taken from the source they arrive in, read through the API surface your ERP already exposes rather than the database.
What it should be allowed to do
Prepare a qualifying cost schedule and a substantiation file and leave it for the tax manager to approve. Reading widely and writing narrowly is the line that keeps this safe.
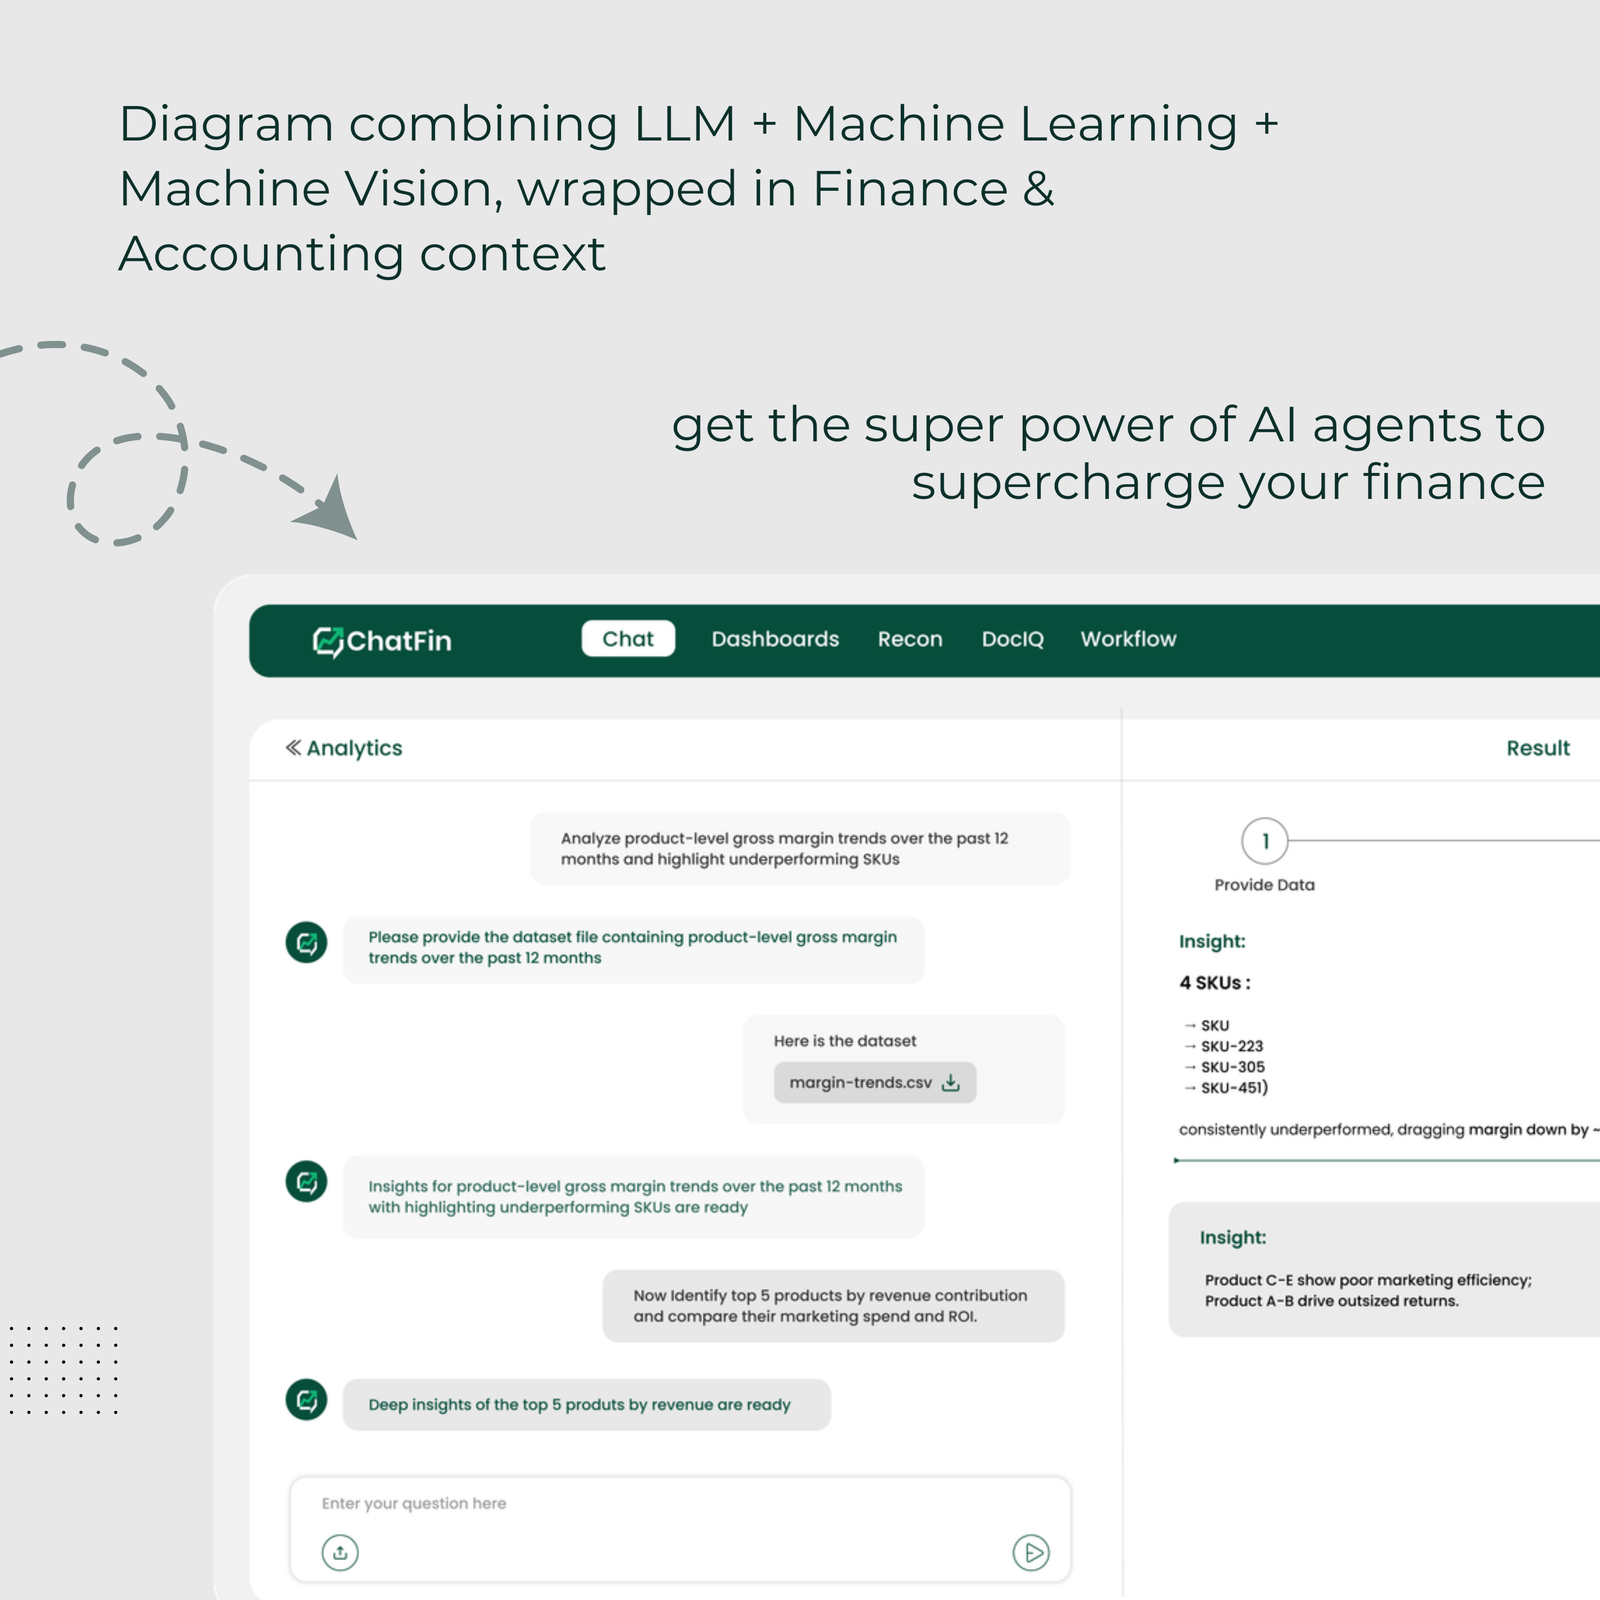
That division matters more than which model sits underneath. An agent that can read project records and technical notes, payroll and contractor cost detail and prior claim documentation while posting only through the validated path a person uses gives you the coverage without handing over the ledger, and ChatFin works that way on every ERP it connects to.
What the agent assembles
The agent collects project evidence through the year, links it to the cost records for the people and contractors involved, and organises it by project.
The qualification determination stays with your tax specialist. What changes is that they start from an organised evidence file rather than from a series of interviews.
Collect evidence continuously
Gather project records, technical discussions and test outcomes as the work happens.
Link activity to cost
Connect qualifying work to payroll, contractor and supply costs at the level your jurisdiction requires.
Organise by project
Structure the file so each project has its uncertainty, its experimentation and its costs together.
Prepare the schedule
Draft the qualifying cost schedule with the evidence referenced for the specialist review.

Working with your specialist, not around them
Nothing here replaces the technical and tax judgment a specialist provides. Qualification rules are detailed and jurisdiction specific, and the positions taken carry real consequence.
What the agent removes is the archaeology. Better inputs generally mean a stronger claim and a shorter engagement, which is a good trade in both directions.
Evidence and linkage
Contemporaneous project records collected and organised, costs linked to activity, schedules prepared.
Qualification and positions
Whether activity qualifies, how to treat borderline projects, and the filing position itself.
Qualification is a specialist judgment
Whether activity qualifies depends on jurisdiction specific rules and carries real consequence if overstated. ChatFin gathers and organises the evidence and links it to cost, and the qualification decision and filing position stay with your tax specialist.
The record kept against research credit substantiation is deliberately plain: the project records and technical notes the agent read, the reasoning it applied, the draft it produced, what the tax manager changed, and the moment it posted. That is the trail an auditor asks for, and it is assembled while the work happens rather than reconstructed afterwards.
The wider argument for that design sits in why finance AI should read widely but write narrowly and connecting without database credentials.
A is prepared, reviewed and approved before it posts, and every step is logged from the source document to the entry. qualifying cost schedule and a substantiation file
How ChatFin builds the file
Evidence is collected as the work happens rather than reconstructed from interviews after year end, including the failed approaches that demonstrate technical uncertainty. Your specialist starts from an organised file per project instead of a series of conversations.
It connects to the ERP, the project tracking system and the payroll system through the interfaces those systems already expose, which keeps the security review short and the setup measured in days rather than quarters.
Collect as work happens
Project records, technical discussions and test outcomes captured through the year.
Link activity to cost
Payroll, contractor and supply cost connected to the qualifying work at the required level.
Organise by project
Uncertainty, experimentation and cost held together per project rather than per period.
Prepare the schedule
Qualifying cost schedule drafted with the evidence referenced for specialist review.
A first run is usually read only against a period you have already closed, so you can compare what the agent found against what your team found before anything is trusted with a qualifying cost schedule and a substantiation file.
The same connection and the same approval pattern carry the next workflow, across NetSuite, SAP Business One, Acumatica and the rest of the stack ChatFin supports.
Claims are rarely challenged on arithmetic. They are challenged on whether the records existed at the time.
ChatFinFrequently Asked Questions
Does this replace our R and D tax specialist?
No. Qualification is a technical and jurisdiction specific judgment that should stay with a specialist. The agent changes what they are given to work with, replacing interviews and reconstruction with an organised contemporaneous file.
What counts as contemporaneous evidence?
Records created while the work was underway: project tracking detail, design discussions, test results and decision records. The specific expectations vary by jurisdiction, which is another reason the specialist relationship matters.
Will engineers have to write documentation for tax?
Ideally not. The approach uses records they already produce. Small improvements in how work is described help, but the objective is to use what exists rather than to add a parallel process.
This page is general information about finance operations and software, not legal, accounting, or tax advice. Confirm treatment for your own entity with your advisors.
Build the substantiation file during the year, not after it.
ChatFin gathers project evidence continuously, links qualifying activity to the costs behind it, and organises the file by project for your specialist.
The qualification judgment stays where it belongs, and the evidence supporting it exists from the period it describes.
Book a DemoSee project evidence organised for a claim.
Bring a quarter of project records and the related cost detail. We will show the evidence organised by project with costs linked, ready for specialist review.